内容简介
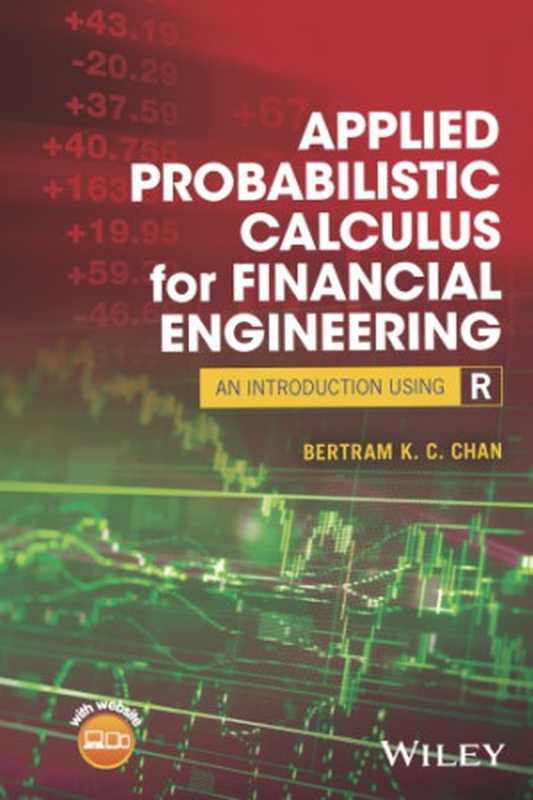
书名:Applied Probabilistic Calculus for Financial Engineering: An Introduction Using R出版社:Wiley
作者:Bertram K. C. Chan
出版年份:2017
电子书格式: pdf
简介:This book provides a comprehensive introduction to probabilistic calculus for financial engineering using R. It covers core concepts like stochastic calculus, Monte Carlo methods, and their applications in financial modeling. Learn how to apply these techniques using R, a powerful statistical programming language. Ideal for finance students and professionals seeking to deepen their understanding of quantitative finance. Explore real-world financial applications with practical examples and detailed explanations.
ISBN:9781119387619, 11193